

















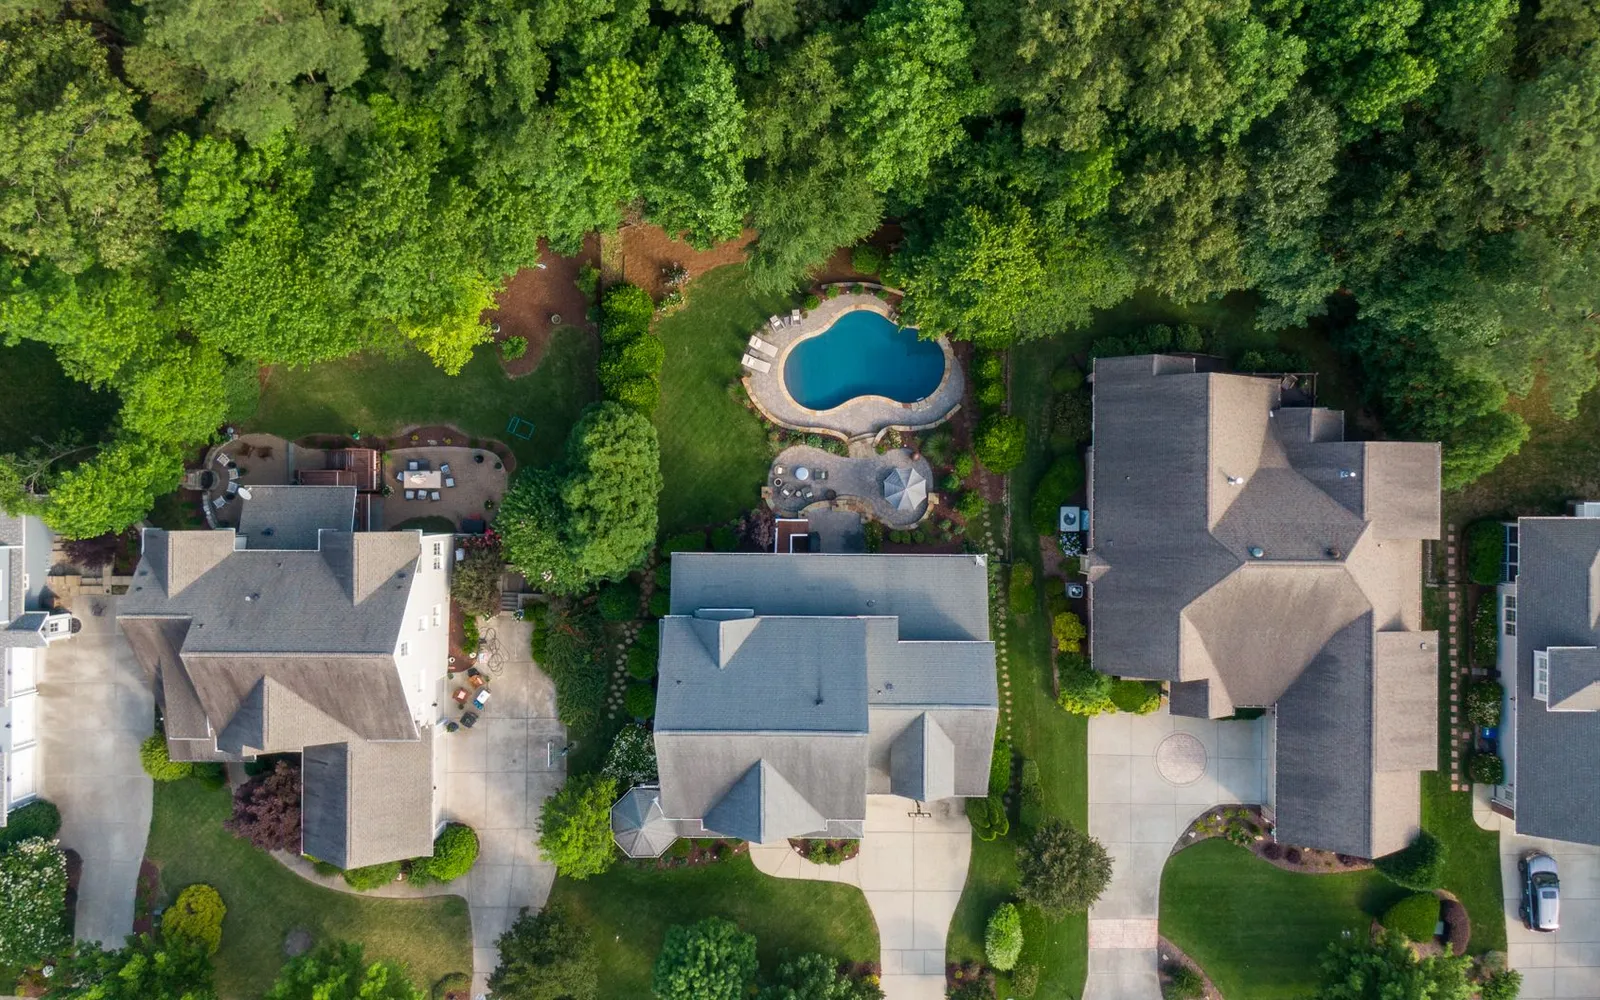
If a Texas insurer turned down your homeowners application this year, there’s about a coin-flip chance the reason leaned on a picture of your house taken from above.
That’s what the state’s own numbers show. We downloaded the raw home insurance file behind the Texas Department of Insurance’s new transparency tool and counted.
What the data shows
Insurers reported 208,919 declination notices on owner-occupied homeowners policies, all sent from April through June 2026. On 108,380 of them, 51.9%, the insurer flagged that its reasons relied on aerial imagery. Add other outside data and the share hits 89.1%.
The pictures weren’t mainly about roofs. Roof condition showed up on only 1,622 declines. The heavy users were “location of risk,” cited on 43,473 declines, with aerial imagery behind 88% of them, and “condition of property, other,” cited on 18,790, with imagery behind 91%.
Nonrenewals look different. Of 54,157 homeowners nonrenewal notices, aerial imagery was flagged on 6,269. The most common answer was “Other, insurer’s action,” the only reason on 22,780 notices, 42%. TDI tells insurers to use that code when they simply don’t cover a certain type of roof.
The fight over the flag
Not everyone wanted this reported. Three commenters on the rule opposed the requirement, and two argued that aerial imagery “is a tool for assessing risk but is not a reason for an underwriting action.” TDI disagreed, pointing to a Texas law that requires insurers to state the source of the information behind the reason. The flag stayed.
Good call. A picture from above shows what your property looked like the day it was taken. It doesn’t show the repair you made last month. If a picture cost you your coverage, you deserve to know a picture was involved.
One more rule to keep handy. TDI said on September 29 that insurers can judge the condition of your roof, wiring or plumbing, but can’t decline or nonrenew you just because the house or its parts are older. Condition counts. Age alone doesn’t.
Do this
Read your notice for the reason and the source. If it says aerial imagery, call the insurer and ask what the image showed and when it was taken.
If the issue is your roof or another visible condition, get a licensed roofer or inspector out, fix what’s real, and send the report and photos to the insurer or your agent. If the notice reads like your roof’s age is the whole reason, cite TDI’s September 29 statement and ask for the condition finding in writing.
Then shop. Get quotes from three or four companies before the old policy ends, and compare with the insurance estimator. If you already did storm-proofing work, check whether Texas’s mitigation discount rules apply.
Stuck? Call the TDI Help Line at 800-252-3439. For how the written-reason law works, see our September explainer. Car insurance got its own data drop, which we ran too.
The fine print on our math
The reasons file counts notices, not companies, and one notice can list several reasons, so shares don’t add to 100. “Aerial imagery” includes notices coded as aerial only and as aerial plus other third-party information, per TDI’s adopted statistical plan. Nonrenewal counts include notices sent before April 1 for policies ending after it, which TDI’s tool also includes.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.
Sources
- 89R HB 2067: reasons for residential property declinations, cancellations, and nonrenewals (Texas Open Data Portal)
- Reasons home and auto insurance policies are declined, not renewed, or canceled (Texas Department of Insurance)
- TDI launches new transparency tool showing why some home policies are declined, canceled, or not renewed (Texas Department of Insurance, September 23, 2026)
- Adopted 28 TAC 5.9503 and 5.9504, Texas statistical plans for residential and auto risks (Texas Department of Insurance)
- Texas homeowners protected from being denied insurance based on roof age (Texas Department of Insurance, September 29, 2026)